Gerindra Reveals Criteria for Prabowo's Vice Presidential Candidates, Must Be Able to Execute Programs
-
News
-
6 minutes ago
This article was translated by AI. Read the original article on Kompas.com. See Original

JAKARTA, KOMPAS.com - Central banks around the world are starting to reassess where they store their gold reserves.
This move does not always mean repatriating gold back to their home countries; it can also involve diversifying storage locations to enhance security, physical access, and liquidity of the reserves.
Krishan Gopaul, Senior Analyst for EMEA at the World Gold Council (WGC), explained that changes in gold storage locations are part of a more active reserve management strategy.
 Gold illustration, gold bars.
In a WGC report titled Why are central banks moving their gold reserves, published Friday (September 18, 2026), Gopaul highlighted the decision by the Dutch central bank, De Nederlandsche Bank (DNB), which relocated around 86 tons of gold from New York, United States, and Ottawa, Canada, to London, England between March and August 2026.
The operation aimed to improve the liquidity and ease of trading their gold reserves while strengthening DNB’s readiness in the face of severe crisis conditions.
However, the move was not simply about transferring 86 tons of gold from North America to Europe.
Approximately 59 tons of gold were sold in New York and replaced with internationally tradable gold in London.
Meanwhile, over 27 tons of gold were physically moved from North America to DNB’s facility in Zeist, the Netherlands. About the same amount of gold was then transferred from Zeist to London.
As a result, the share of the Netherlands’ gold reserves stored in London rose from 18.1 percent to 32.1 percent. This portion even surpassed the amount kept domestically in the Netherlands, which stood at 30.8 percent.
Meanwhile, the amount stored in New York and Ottawa declined to 18.5 percent each, down from 31.3 percent and 19.7 percent, respectively.
This shift demonstrates that central banks’ strategies regarding gold reserve locations do not always aim simply to bring gold back home.
According to Gopaul, DNB’s decision reflects a shift in how central banks view gold storage.
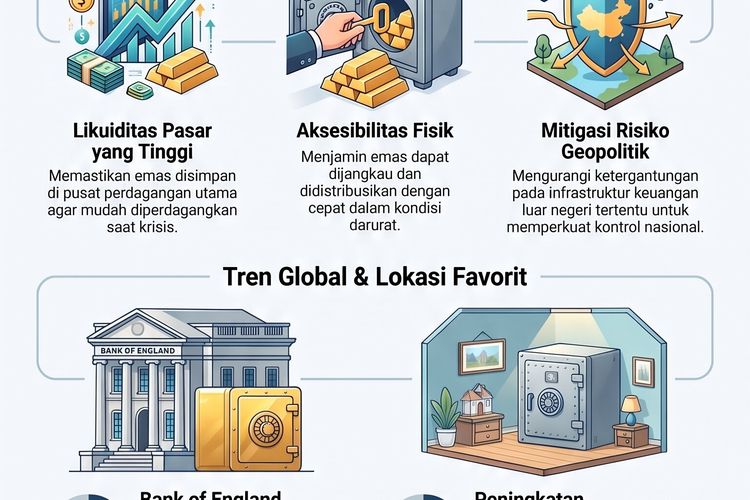
“Central banks are increasingly optimizing three considerations: storage risks, physical accessibility, and market liquidity,” he said in the report.
Moving gold reserves back home is actually not a new phenomenon.
Gopaul noted that Germany repatriated about 930 tons of gold from London to Frankfurt in 2000. Then, between 2013 and 2017, Germany’s Bundesbank moved another 674 tons of gold from New York and Paris back to Frankfurt.
Venezuela also returned 160 tons of gold from foreign institutions between 2011 and 2012. The Netherlands moved 122.5 tons from New York to Amsterdam in 2014, while Austria relocated 90 tons from London between 2015 and 2018.
Subsequently, other countries adjusted their gold storage locations as well. Turkey altered some of its overseas gold storage, while Hungary and Poland transferred physical reserves to domestic storage.
Serbia reportedly repatriated about 13 tons of gold between 2021 and 2022. India has gradually increased domestic gold holdings since 2022, with a sharp rise in relocation rate after March 2023.
France also changed the geographic distribution of its gold reserves during 2025-2026, selling 129 tons stored in New York and acquiring an equal amount in Europe.
However, the Banque de France did not describe this operation as a physical relocation.
The WGC categorizes these developments into three overlapping waves.
The first wave was an initial evaluation of reserve location arrangements. Germany’s gold movements in 2000 exemplify how geographic distribution of gold reserves was reconsidered before repatriation became a geopolitical issue.
The second wave, roughly between 2011 and 2019, focused more on national control and public confidence. For example, Venezuela framed its decision in terms of increasing national control.
Other central banks took a more balanced approach. Germany aimed to keep half of its gold reserves in Frankfurt.
Austria likewise stores half of its gold domestically but retains large reserves in London and Switzerland to ensure access to international markets.
Poland combined gold repatriation with substantially increasing its reserves.
According to Gopaul, the third wave is more complex. Rising geopolitical uncertainty has made central banks pay more attention to jurisdiction, access to gold in crises, and reliance on foreign financial infrastructure.
Central banks in various countries have started reassessing their gold reserve storage locations.
However, recent developments in France and the Netherlands show that central bank responses do not always entail storing gold domestically.
DNB exemplifies this strategic shift.
In 2014, the Dutch central bank moved gold from New York to Amsterdam to increase domestic holdings. Conversely, in 2026, DNB shifted gold from North America primarily to London to make reserves easier to use.
Gopaul noted that both decisions led to different geographic locations but shared the same goal: building resilience through better-distributed reserves.
The 2026 Central Bank Gold Reserves Survey by WGC also shows gold storage isn’t moving solely toward domestic holdings.
The Bank of England is the most frequently cited storage location among respondents, with 57 percent referencing it. Meanwhile, 49 percent said they store at least part of their gold reserves domestically.
The survey involved 69 central banks holding gold reserves.
In the previous 12 months, 9 percent of respondents increased domestic gold holdings, while simultaneously, 10 percent diversified overseas storage locations.
Looking ahead 12 months, 7 percent plan to raise domestic storage, whereas 9 percent expect to further diversify overseas storage.
The proportion intending to diversify foreign storage rose from 2 percent in the previous survey.
These findings indicate growing attention by some central banks to evaluate and diversify gold storage arrangements.
“Some increase domestic storage, while others expand the number of foreign locations they use. This shows storage diversification, not a uniform shift to domestic storage,” Gopaul explained.
Changing the location of gold reserves does not necessarily mean central banks are preparing to sell them.
Gopaul clarified that relocating gold to more liquid markets may look like gearing up for sales, but liquidity provides options under extreme conditions.
Gold placed at major trading hubs can be mobilized more efficiently. However, increased capability does not imply central banks plan to use their gold reserves.
DNB explicitly stated it does not anticipate using the gold. The relocation aims to ensure reserves are more quickly accessible if needed.
The 2026 WGC survey also shows only 1 percent of respondents expect their gold reserves to decrease in the next 12 months. Conversely, 45 percent expect reserves to increase.
Therefore, Gopaul said recent gold reserve relocations should not be automatically interpreted as evidence that central banks are preparing sales.
On the contrary, these examples show that gold location has become an important part of active reserve management.
In the future, adjusting storage locations may also involve more storage centers.
Singapore has announced plans to provide gold storage services for central banks and foreign sovereign entities, while Hong Kong is expanding its clearing, settlement, and gold storage infrastructure.
According to Gopaul, these developments demonstrate that security is no longer the only consideration in determining gold reserve locations.
For some central banks, gold must also be accessible, tradable, and distributable across multiple reliable locations during times of stress.